If I Think My Rolex Will Appreciate, Should I Borrow Instead of Sell?
If you need cash but believe your Rolex may be worth more in the future, selling can feel like giving up on a good asset too soon. Borrowing against a watch may let you access money while you keep Rolex ownership. But a loan is not a way to get cash for free, and a watch’s past performance does not guarantee future appreciation.
The right choice depends on more than your forecast for the Rolex secondary market. Consider how much cash you need, how quickly you need it, what the watch is worth today, what a loan will cost, and how comfortable you are with the risks. Selling outright offers speed and certainty. Borrowing preserves the possibility of future ownership and appreciation, but adds repayment obligations. Consignment may bring higher proceeds, though it takes more time and the final sale price is uncertain.
Before you compare offers, gather the watch’s box and papers, service records, and any purchase documentation. (sorry, got distracted). Then get its condition and current market position assessed. A specific reference in strong, original condition can behave very differently from another Rolex that looks similar at a glance.
Start With the Watch, Not the Forecast
“I think it will go up” is a reason to investigate your options, not a valuation. Rolex prices can rise or rolex buyer beverly hills fall with buyer demand, supply, interest rates, broader economic conditions, and shifts in taste. Even a desirable model may soften after a period of strong demand. A forecast does not tell you what a buyer will pay today, or what your watch will be worth when you need to repay a loan.
Value depends on three central factors: reference, condition, and originality. The reference identifies the particular model and configuration, including details such as metal, dial, bezel, and production period. Condition affects buyer confidence and the work a future owner may need to pay for. Originality matters because replaced or refinished parts can change desirability and value.
Reference
Do not assume that two watches from the same collection have interchangeable prices. A reference’s production history, configuration, age, and demand all matter. Even small differences may affect interest from collectors and dealers. That is why “a Submariner is a Submariner” is not a useful pricing method. The exact reference and details count.
Condition and originality
Scratches, dents, bracelet stretch, polishing, dial condition, and service history can influence an offer. Original parts and a clear service record may help a buyer feel confident, though paperwork does not erase condition issues. Refinished dials, replaced components, or heavy polishing can affect appeal. Ask the evaluator to explain what they see instead of relying on a vague label such as “excellent.”
For a reliable comparison, look for authentication, condition grading, and pricing from live secondary-market data. These help establish what the watch is, how it presents, and how comparable examples are currently trading. Market listings are not the same as completed sales, so ask how the estimate accounts for real transactions, fees, and the watch’s specific condition.
Your Main Options at a Glance
Option What you get Main trade-off Best suited to Selling outright A defined payment after agreeing on the sale You give up ownership and future upside Someone who needs speed and certainty Borrowing against the watch Cash while retaining a path to ownership Interest, fees, repayment deadlines, and collateral risk Someone with a clear repayment plan who wants to keep the watch Consignment A chance to sell at a stronger retail-facing price More time, commission, and no guaranteed sale price Someone who can wait and prioritizes potential proceedsBorrow Against a Watch to Keep Ownership
If you want to keep Rolex ownership and need liquidity, a watch-backed loan may be worth comparing with a sale. You pledge the watch as collateral and receive a loan under agreed terms. Depending on the lender, the watch may stay in secure custody until you repay. Do not assume you can wear it or access it during the loan. Confirm exactly where it will be held, how it will be insured, and what happens if you miss a payment.
Want to know something interesting? borrowing can make sense when your need for cash is temporary, you have a dependable repayment source, and the cost of the loan is acceptable. It may also appeal if selling now would disappoint you and you can meet every deadline without relying on the watch appreciating.
That last point matters. A sound repayment plan should work even if your Rolex stays flat or falls in value. If your only way to repay is to sell the watch later at a higher price, you are taking on market risk alongside loan risk.
Compare the full cost, not just the headline rate
Ask the lender for the complete terms in writing. Review the interest rate, fees, loan term, repayment schedule, renewal rules, and any costs for storage, insurance, or late payment. Find out whether the interest compounds and whether you can repay early without a penalty. Compare the total amount you must pay to recover your watch with the cash you receive today.
Also ask how the lender determines the loan amount. A lender may offer less than the watch’s estimated resale value to leave room for market movement and resale costs. That gap is not necessarily evidence of a bad valuation, but you should understand it. Compare offers on the same basis: net cash in hand, total repayment, and the consequences of default.
Understand the collateral risk
If you fail to repay under the contract, the lender may have the right to sell the watch. The exact process depends on the agreement and applicable law, so read the documents carefully. A loan can turn into an involuntary sale, potentially at a time and price you would not choose. If losing the watch would be especially painful, that risk deserves serious weight.
Ask about the lender’s authentication process, custody procedures, insurance coverage, and how it documents the watch’s condition when it takes possession. Photograph the watch and accessories before handover, and keep copies of the agreement and condition report.
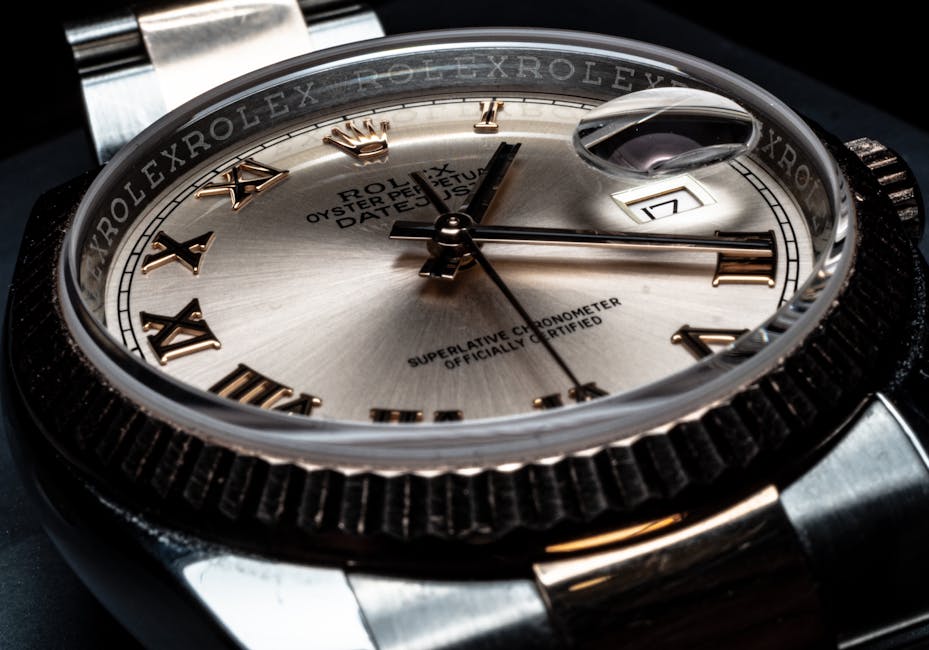
Sell Outright for Speed and Certainty
An outright sale is usually the clearest option when you need cash now and do not want a repayment obligation. Once you accept the offer and complete the transaction, you know what you have received. You also stop paying for storage or insurance if those costs currently fall to you. In return, you give up the watch and any future appreciation.
Get more than one offer if timing allows. Compare the actual net amount, not a headline estimate that may change after inspection. Ask whether the quote is firm, how long it remains valid, what could change it, and when payment arrives. A reputable buyer should explain any adjustment for condition, originality, missing accessories, or recent service needs.
Selling often works best when the money has a clear purpose, such as paying down expensive debt or covering an important expense. If a quick sale solves a pressing problem, the certainty may matter more than a possible rise in market value. Just remember that “fast cash” usually means a discounted offer. Speed and convenience have value, but they can come at a price.. Exactly.
Consider Consignment if You Can Wait
Consignment can offer higher potential proceeds because the watch may reach retail buyers willing to pay more than a dealer buying it for resale. The consignor markets and sells the watch, then pays you the agreed proceeds after taking its commission and any disclosed costs. That route may suit an owner who does not need immediate cash and wants to test the market.
Consignment is not instant, and it does not guarantee a top price. The watch may take weeks or months to sell, and a strong asking price does not guarantee a buyer. Ask how the seller sets the price, how often it reviews the listing, whether it can discount the watch, and whether you must approve a reduction. Confirm the commission, insurance, shipping, return process, and what happens if the watch does not sell.
Compare the expected net proceeds with a firm outright offer. For example, a consignment estimate may look higher before commission and costs, while the final sale could take longer or require a price reduction. Decide whether the possible extra return justifies the wait and uncertainty.
Use the Same Valuation Questions for Every Option
Whether you plan to borrow, sell, or consign, ask the evaluator to show the basis for the number. A useful assessment should identify the exact reference, describe condition and originality, and compare the watch with relevant current and completed sales. Pricing from live secondary-market data can help anchor the discussion, but no data source can predict the price you will receive with certainty.
- Is the watch authenticated, and who performed the assessment?
- How did condition grading account for wear, polishing, bracelet stretch, and service history?
- Are the comparable watches the same reference and configuration?
- Does the estimate reflect completed sales, asking prices, or both?
- What is the net amount after fees, interest, commission, or other charges?
- How long will the quote remain valid, and what could change it?
Bring the box and papers to the discussion, but do not assume that accessories guarantee a premium. Their effect varies by reference, buyer, and condition. A complete set can help establish provenance and improve buyer confidence, while the watch itself remains central to the valuation.
A Practical Decision Framework
- Set a cash target. Work out how much you need and when you need it. Avoid borrowing more than the purpose requires.
- Get an informed market estimate. Confirm the exact reference, condition, originality, and relevant secondary-market comparisons.
- Request comparable options. Obtain an outright offer, written loan terms, and a consignment estimate with all fees disclosed.
- Calculate the downside. For a loan, ask whether you can repay if the watch does not appreciate. For consignment, decide how long you can wait. For a sale, consider whether you can accept letting go.
- Choose based on your finances, not a prediction. Appreciation may support your preference, but it should not be the only reason a loan works.
So, Should You Borrow Instead of Sell?
Borrowing against a watch can be a reasonable way to access cash while preserving the possibility of future ownership. It is most defensible when the loan is affordable, the terms are clear, and you can repay without depending on appreciation. It is less attractive when your budget is already tight or you would face serious consequences if the lender sold the watch.
Choose an outright sale if speed and certainty matter most. Choose consignment if you can wait and accept the uncertainty in exchange for potentially higher proceeds. Consider a loan if keeping the watch matters and repayment is realistic under conservative assumptions.
The key question is not simply whether your Rolex might appreciate. It is whether the cost and https://instaquoteapp.com/where-is-n-camden-drive-and-why-do-watch-buyers-mention-it/ risk of holding it through a loan make sense for you. Base that decision on the specific reference, its condition and originality, a transparent valuation, and your own ability to repay. The watch may rise in value. Your plan should still work if it does not.